The U.S. dollar remained largely unchanged on Tuesday as expectations for a more dovish Federal Reserve outlook were offset by renewed concerns over the Middle East and ongoing uncertainty between Washington and Tehran.
The U.S. dollar index, which tracks the greenback against a basket of six major currencies, traded just above unchanged at 99.66 after falling to a more than two-month low of 99.29 in the previous session.
Bond Market Volatility Weighs on Currency Markets
Interest rates remained the main focus for currency traders as a sell-off in U.S. Treasury bonds extended into global fixed-income markets.
The U.S. 30-year Treasury yield reached a session high of 5.335%, its highest level since June 2007, before easing to 5.284%. Longer-term yields have faced greater pressure as investors assess inflation risks, government debt concerns and expectations for future monetary policy.
The bond sell-off continued despite softer U.S. consumer and producer inflation data released last week. Rising oil prices linked to Middle East tensions have renewed inflation concerns, while large bond issuance from major technology companies funding artificial intelligence infrastructure has added to worries around debt supply.
Markets are now watching the Federal Reserve’s July meeting minutes for additional clues on the central bank’s policy direction. Investors are particularly focused on whether the minutes provide further details on the three regional Fed presidents who dissented from the decision to keep rates unchanged.
Oil Prices Extend Gains as Hormuz Tensions Continue
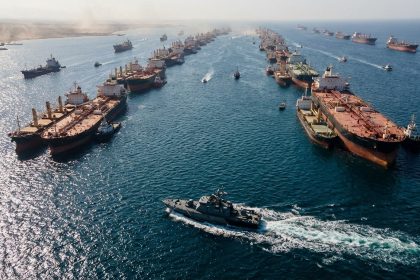
Oil prices continued to rise on Tuesday as the United States and Iran remained locked in a dispute over the Strait of Hormuz.
Brent crude futures, the global benchmark, increased 0.2% to $91.02 per barrel after briefly reaching $92.
The move followed comments from President Donald Trump that the U.S. naval blockade of Iranian ports remained active and that the Strait of Hormuz was open. Iranian officials disputed those claims and said Washington would need to meet certain conditions before the waterway could reopen.
Iran has also been working on a framework with Oman regarding management of the strait, while tensions remain elevated over the future of shipping activity through the key energy route.
Yen Weakens Toward Key 160 Level
The Japanese yen weakened for the fourth time in five sessions, with USD/JPY rising 0.1% to 159.61.
The yen has surrendered roughly half of the gains achieved after a joint intervention by Washington and Tokyo at the end of July. The currency is again approaching the 160 level, which has previously triggered intervention concerns from Japanese authorities.
Despite signals from the Bank of Japan that rate hikes could accelerate as early as September, continued demand for carry trades and differences in two-year bond yields have continued to pressure the yen.
The euro slipped slightly to $1.1576, while the British pound declined 0.1% to $1.3535.
Rupee Falls Despite RBI Support Measures
The Indian rupee continued to weaken, with USD/INR rising 0.3% to 95.839, its highest level since July 28.
Higher oil prices have increased pressure on energy-importing economies such as India by raising concerns over the current account deficit. The broader U.S. bond market sell-off has also contributed to foreign capital outflows.
The decline came despite continued intervention from the Reserve Bank of India, which has reportedly been selling dollars in the spot market to limit further currency weakness.
The RBI has also taken steps to reduce speculative pressure by tightening rules around foreign currency deposit swap facilities after inflows exceeded $50 billion.