X Launches Payment Services for More Users
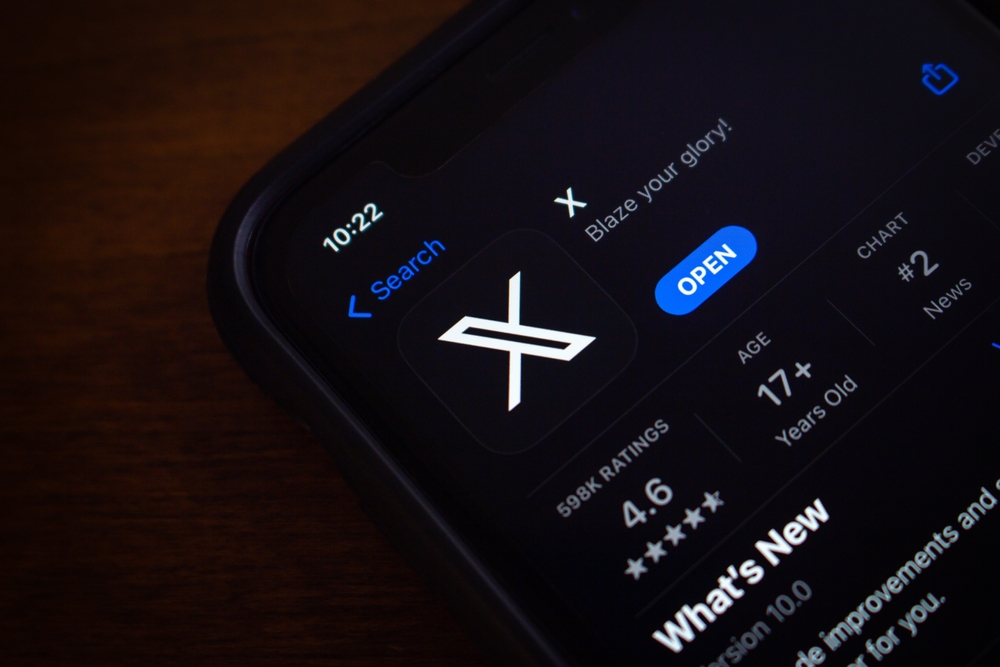
X has expanded access to X Money, its digital payments platform that allows users to manage financial services directly within the social media app.
The service was previously available only as a limited test for select premium subscribers since late June. The wider rollout allows more users to access features including deposits, peer-to-peer payments, bill payments, wire transfers and cheque mailing without leaving the X platform.
Deposits Backed by FDIC Insurance
User deposits are held through Cross River Bank, a New Jersey-based financial institution that provides banking infrastructure for several fintech companies.
The deposits are insured by the Federal Deposit Insurance Corporation (FDIC) for up to $250,000, providing users with similar protections available through traditional banking services.
Elon Musk’s Vision for an All-in-One App
The launch reflects Elon Musk’s long-term ambition to transform X into a broader digital ecosystem similar to China’s WeChat, which combines messaging, shopping and payments in a single platform.
X Money announced that deposits could earn an annual percentage yield of up to 6%, exceeding rates offered by many traditional savings accounts in the United States.
Premium+ subscribers can access the highest available rate directly, while Premium subscribers must meet direct deposit requirements to qualify.
X Money Enters Competitive Payments Market
Cross River described X Money as the first government-insured banking platform in the United States built on a social network.
The service places X in competition with established digital payment platforms such as PayPal’s Venmo, Block’s Cash App and SoFi, while leveraging the company’s large user base.
Regulatory Questions Surround New Service
Before the launch, X Money faced scrutiny from lawmakers in Washington.
In an April letter, Senator Elizabeth Warren questioned how the platform would generate enough revenue to support the promised deposit yields.
She also raised concerns about Cross River Bank, citing previous enforcement actions by the FDIC related to the bank’s lending practices.